

2026-10-31 00:11:00
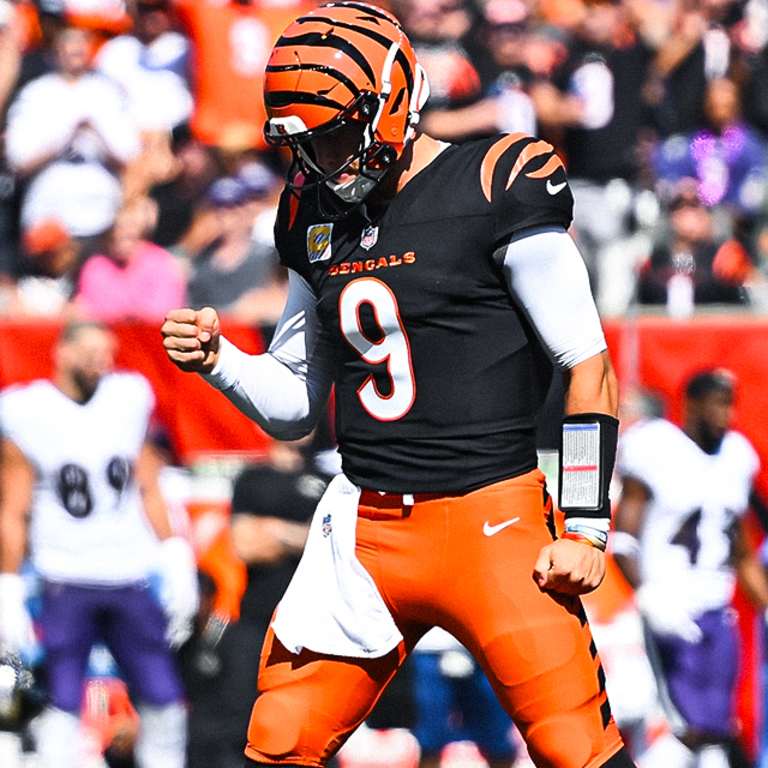
Joe Burrow is once again among the NFL’s elite quarterbacks. Through five weeks of the 2026 season, he ranks fourth in touchdown passes, sixth in passing yards, and leads the league in completion percentage at over 70%.
Yet, what sets him apart isn’t physical. It’s mental. Burrow has a nearly perfect level of confidence, which has been calibrated over time.
Calibrated?
Yes, calibrated.
Let me explain.
When Burrow was just nine years old, his AAU basketball team was trailing by eight points with thirty seconds left. His coach thought the game was over.
Burrow didn’t.
He scored nine straight points, including several consecutive free throws, and somehow won the game.
Afterward, Burrow’s coach, a sociology professor at Ohio University, pulled his parents aside and told them their son possessed an unusual quality. His blood pressure, he said, appeared to be the same whether he was shooting a basketball, cutting the lawn, or pulling someone out of a burning building. He was unfazed, regardless of the task.
Then the coach paused before telling them he was thankful their son was using his talents for good. Otherwise, he could be the next Dexter, the fictional serial killer.
Thankfully for Burrow, his parents, and Cincinnati Bengals and LSU Tigers fans alike, that confidence was channeled in the right direction. Over the past decade he has won a national championship and a Heisman Trophy, earned multiple trips to the NFL Pro Bowl, and came within minutes of winning the Super Bowl in 2022.
The older I get, the more I appreciate how much confidence matters. In fact, I am now convinced it might be the most significant differentiator in many walks of life.
But here’s the critical nuance: it’s not about having “a lot” or “a little”.
It’s about calibrating whatever amount of confidence you have.
For some people, confidence needs to be unlocked. For others, it needs to be reined in. And for people like Joe Burrow, the challenge is channeling it in the right direction.
Too little confidence can prevent someone from taking risks, facing challenges, or even engaging at all. Meanwhile, too much can morph into arrogance. Taken too far, it convinces someone that the rules, the odds, or even reality itself doesn’t apply to them.
The key is finding the right balance.
I witness this every day with my two sons.
My younger son, who is about to turn eight, thinks he can rule the world. There is absolutely no reason for him to possess this much confidence. He hasn’t earned it. He hasn’t justified it. He just has it. And, in many ways, it’s wonderful. Very few things scare him. He’s adventurous. He jumps into nearly everything he does with reckless abandon.
This extreme level of confidence might be his greatest strength. Yet, it has the potential to become a material weakness if he doesn’t learn to keep it in check.
My older son has confidence too, but his is more like a flame that needs oxygen. It often requires encouragement before it begins to grow. Yet when it does, you can see it. He consistently surprises me with what he is willing and capable of doing.
Neither is better.
They’re just different and in need of different levels of calibration.
But how is someone supposed to find the right level?
First, calibrating confidence starts with the people who surround you or you surround yourself with. To this point, while Burrow’s coach may have sounded like he was complimenting his star player, I actually think he was directing his comments at his parents.
Burrow’s confidence was the easy part. He simply had it. The challenge was channeling it into productive use, which, as Michael Moritz of Sequoia Capital said on The Outsider podcast, is the essence of parenting.
That said, we obviously can only control this to a point. Our parents are ours whether we like it or not. The same is often true of our teachers, coaches, and bosses.
However, what we can do is identify those who bring out the best in us, determine what makes them unique, and seek out more people like them.
Personally, I’ve had countless teachers, coaches, and bosses. Unsurprisingly, I had a lot of good, or even very good ones, but only a few were truly great.
So, what made them different?
For one, they didn’t treat everyone with a broad brush. Knowing that people are wired differently, they took the time to figure out what made people tick and adjusted accordingly.
In many ways, it’s the same lesson I’m learning from my sons. One needs to be encouraged to take more risks. The other occasionally needs to be reminded that he isn’t invincible. Treating them the same way wouldn’t necessarily bring out the best in either of them.
The best teachers, coaches, bosses, and parents understand this. In doing so, they become what are often called force multipliers.
Latch on to these people. Study them. Work for them. Hire them.
Second, confidence is calibrated by pursuing hard things and experiencing difficult moments. Even Joe Burrow needed this.
Burrow arrived at Ohio State as a highly recruited quarterback with every expectation of becoming the starter. Instead, he spent three years as a backup, largely watching games from the sideline. In doing so, it humbled him and he said as much after being drafted by the Bengals, admitting that his confidence was really shaken as a result of his experience in Columbus and that he didn’t know if he had what it takes. Ironically, his two teammates who started over him — J.T. Barrett and Dwayne Haskins — had little-to-no success in the NFL.
Yet Burrow didn’t transfer when things got difficult. He stuck it out, graduated, and then looked for a fresh start. And when he did, he didn’t seek out a lesser program where starting might be easier. He chose LSU.
Two years later, he produced one of the greatest seasons in college football history, winning the national championship and Heisman Trophy.
Which brings me to something former Navy SEAL commander William McRaven said he looked for in a SEAL. Intelligence mattered, but what really mattered was whether someone could keep thinking when cold, wet, exhausted, and surrounded by adversity.
In McRaven’s words, he wanted someone with “just enough swagger, but also just enough humility.” This is the best description I have heard for calibrated confidence.
Enough swagger to believe you can figure things out, yet also enough humility to recognize that you don’t have all the answers.
Enough confidence to take a risk. Enough humility to know you might be wrong.
Enough confidence to lead. Enough humility to listen.
And maybe that’s why I keep coming back to Joe Burrow.
For all his confidence, Burrow seems to have a good sense of where this thin line resides.
When a reporter once compared him to Tom Brady, Burrow quickly shut it down, saying: “Please don’t compare me to the best player of all time. Let me do my own thing.”
He wasn’t shrinking from the comparison. He wasn’t embracing it either. He was simply confident in what he could become without pretending he had already become it.
That’s a hard balance to strike.
Confidence isn’t about having more.
It’s about having the right amount.
That’s calibration.
2026-10-14 17:16:00
Collaborative Fund is hiring an Investment Associate to join our team in New York.
We back entrepreneurs pushing the world forward. We look for businesses that can generate exceptional financial returns while making the world better or more interesting, with investments spanning Consumer, AI, Infra, Money, Health, and Energy.
This is a highly autonomous, hands-on role across the full range of early-stage investing. You will work closely with our Partners and the broader team to source and evaluate new investments, develop investment ideas, and support existing portfolio companies.
This is a two-year Associate program, designed to provide broad exposure to early-stage venture investing.
We are looking for people with roughly 3-5 years of professional experience who are deeply interested in startups and tech. Strong candidates may have spent that time building, operating, investing, or advising in and around technology companies.
Candidates should already be engaged with the startup ecosystem and excited by the range of areas in which we invest. We are looking for someone who is:
This role is based in New York and is primarily in person. The person in this role will work regularly from our Manhattan office, bring strong connections within the New York startup community and travel to the Bay Area to stay closely connected to the West Coast startup ecosystem.
Complete the application linked here. We will review applications on a rolling basis.
2026-10-14 03:23:00
🎙️ Listen on Spotify, Apple, or wherever you get your podcasts.
Matt Sonsini is Managing Partner and co-founder of Ravello Impact, and the former CEO of The Sobrato Organization. Before moving into investing and philanthropy, he spent almost two decades as a corporate lawyer in Silicon Valley, working with startups, venture capitalists, and public companies.
In this conversation, he explains why waiting to give can become its own excuse, why measuring philanthropic impact is harder than measuring investment returns, and what founders sacrifice when they chase the highest valuation. He also revisits the boardroom moment when a CEO quit on the spot and the unlikely IPO that still stands out decades later.
“Well, I guess if you’re Warren Buffett, you have a reasonable shot at compounding capital at a greater rate than the world’s problems are compounding. But for mere mortal investors, I’m personally doubtful that’s the case.”
Giving has its own risk-return spectrum: Local food banks offer immediate, measurable results. Systemic change demands more time, more resources, and a willingness to accept uncertain outcomes. Sonsini approaches those choices as a portfolio, allocating across both.
Good intentions need honest feedback: A business with a bad product hears from the market. A donor can still get a gala and a name on a building without knowing how much good the money did. He also argues that funders, nonprofits, and government need to collaborate more to make their resources count.
A higher valuation can hide a worse deal: Senior liquidation preferences and separate investor approval rights can create conflicts when growth stalls. He urges founders to resist trading away important terms to reach a headline valuation.
Venture’s failures are part of the process: Funding booms draw talent and ideas into new markets. Many companies fail in the correction, but investors cannot know the eventual winners in advance. He sees that experimentation as necessary.
Optimism takes practice: Legal training taught Sonsini to look for downside. Investing taught him that optimism is essential. The best advisers, he says, tell clients which risks matter and which they can stop worrying about.
00:00 – Introduction to Matt Sonsini
01:03 – Give Now or Compound for the Future?
05:01 – Measuring Impact and the Risk of Virtue Signaling
07:52 – Building a Philanthropic Portfolio
09:20 – Government, Philanthropy, and the Need to Collaborate
12:43 – The Term-Sheet Rights Sonsini Would Remove
16:31 – Why He Dislikes Pay-to-Play Provisions
17:00 – Don’t Chase the Valuation
19:18 – Why More Venture Capital Doesn’t Eliminate Failure
24:25 – A Boardroom Takeover and an Unlikely IPO
29:17 – Learning to Be an Optimist
31:49 – Closing Remarks
2026-09-17 19:21:00
In a market saturated with frothy AI bets, we believe our investment in the paradoxical Dr. Max Goldstein, a practicing family physician and a Mendocino farmer, is just what the doctor ordered.
Born out of organic demand from over 30,000 patient visits, Dr. Max spent 5 years prototyping products in his kitchen before commercializing his modern apothecary.
In an era where parents are expected to be amateur toxicologists, navigating complicated ingredient labels and judging Yuka scores in their diaper caddies… it’s a relief to find products with clean ingredients that just work, made by a family for families.
With less than $10k of marketing spend, Dr. Max’s is already the top selling brand in children’s body care in Erewhon. We believe their organic traction is setting the foundation to build the next generational brand in natural, efficacious personal care. Brands with similar perspectives like Burt’s Bees (sold for $925m in 2007), Coterie (sold for a reported $1b+) and Eucerin + Aquafor generating €1.5b revenue annually, establish the economic opportunity.
Dr. Max’s formulas are EWG verified and accepted by the National Eczema Association, but strong cohort data and organic customer acquisition are the best indications that the products just work.
Parents in Dr. Max’s practice were looking for products they could trust so he made them in his own kitchen, from ingredients grown on his farm. Formulas have been perfected over time from patient feedback, and the brand has been building with his community.
Baby care is one of the highest consideration purchases for families. We believe that Dr. Max’s has the potential to expand their platform from a trusted first product into a lifetime of family care.
In consumer, few are more loyal than a parent who has found the “thing” that finally works. We’re proud to back Dr. Max and his co-founder Erin as they build it.
2026-08-18 21:57:00
“Fries with dinner but no dessert counts as a win.”
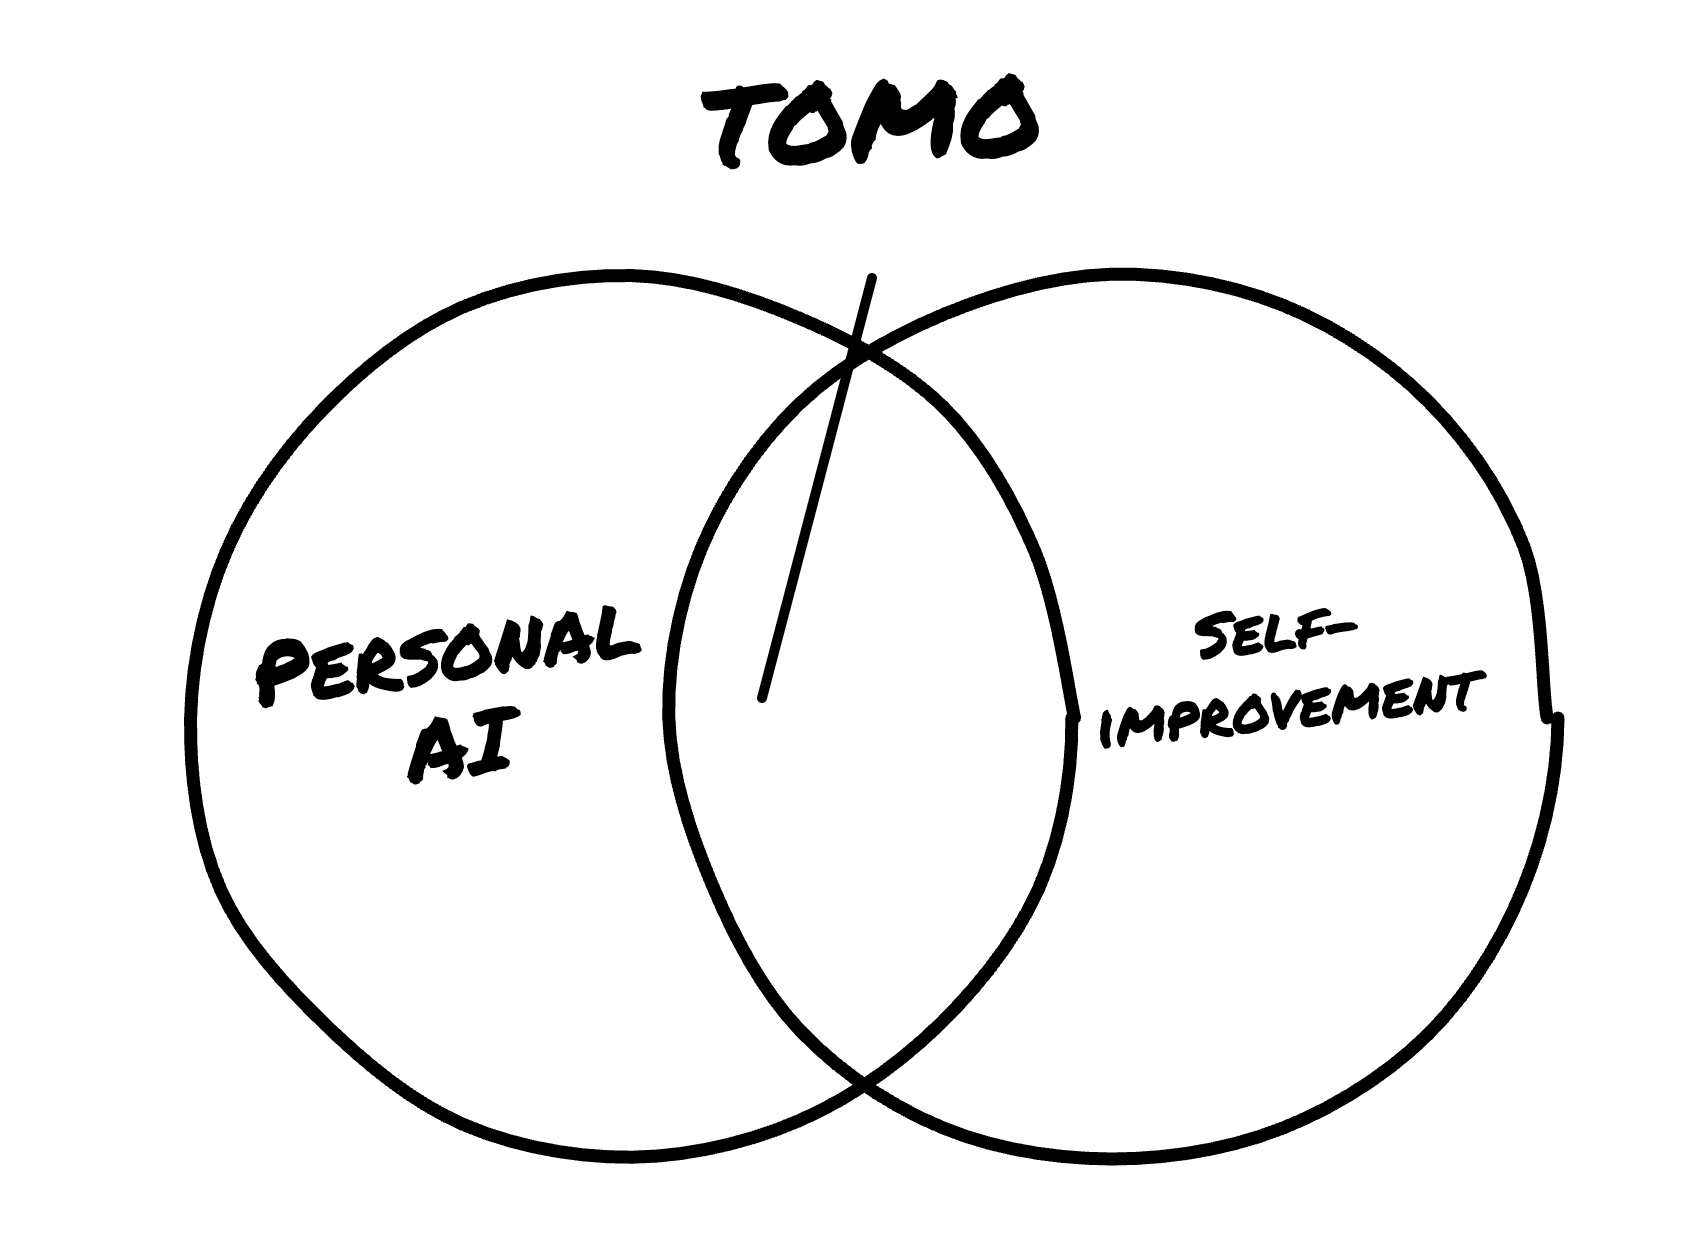
Who will build the first era-defining consumer AI company? Even the beloved AI tools we already rely on are only one model release away from obsolescence. The lasting advantage will come from products people emotionally trust, build habits around, and fold into their identities. Tomo extends beyond productivity into the higher-order value of wellbeing, and has the founder and product philosophy to define their category, if not the era.
Habit trackers, calorie counters, and budgeting apps attempt to manage your life in isolation and reward unbroken streaks. But your finances, fitness, sleep, and stress are interconnected, and imperfect. As a unified AI layer holding context across all of it, Tomo intervenes at the right moment to change behaviors and outcomes. That context also allows for grace: fries with dinner but no dessert counts as a win. Forgiveness is the retention mechanic the category has been missing.
Tomo delivers on a far-off promise of AI today by shipping adaptive interfaces that intuit user’s needs: a runner preparing for a race gets a training tracker, someone who can’t get out of bed gets a game that only unlocks during their morning routine. As priorities and goals change, the experience evolves, deepening personalization and increasing loyalty.
Justin and Raymond are as product-obsessed as founders get, dissecting divergent use cases through hours of interviews and observation and inserting their own taste when it’s needed
Traction is exceptional. 10,000+ paying subscribers in three and a half months, entirely by word of mouth, while still in stealth. Users text Tomo 20 of every 30 days, engagement that rivals the stickiest consumer apps.
Generational consumer AI companies will be the ones people trust with their lives — in all their fullness and chaos — not just their work. We believe Tomo is building for that future.
2026-07-30 21:52:00
🎙️ Listen on Spotify, Apple, or wherever you get your podcasts.
Jacob Hodes is a partner and Chief Investment Officer of Private Investing at Brown Advisory, the Baltimore firm descended from Alex. Brown & Sons — the first investment bank in the United States. He got there by way of Goldman Sachs, law school, and Skadden, a path he describes as meandering.
In this conversation, he explains why he’s both the loudest advocate for private markets at his firm and increasingly nervous about where they’re headed, what a post-industrial city does to an investor’s judgment, and why the junior people who rise fastest are rarely the ones with the best pedigree.
“You think you do, but committing yourself for 10 years is really tough. … If half of all marriages end in divorce, that’s usually within 10 years. You probably feel much more strongly about getting married than you do about making an investment.”
Private markets were built on information asymmetry: A century ago the Rockefellers and Carnegies could make private bets because their operating businesses gave them a data set nobody else had. That edge migrated to institutions with the balance sheets to go long — and the fund structures followed.
Illiquidity is underestimated by everyone who hasn’t lived it: A ten-year commitment outlasts half of all marriages. As private vehicles push downmarket, Hodes expects investors to fall out of love with positions they can’t exit.
The asset-liability mismatch is the risk to watch: Semi-liquid vehicles wrap multi-year illiquid assets in structures promising something closer to daily liquidity. Smart people will eventually solve it; the road there will be bumpy.
Underdog geography sharpens judgment: Working from Baltimore rather than a coastal financial center means finding value where others don’t look — and holding onto discipline when you’re across the table from a high-flying founder.
Read newspapers from places you don’t live: Local papers from cities and countries outside your own break the echo chamber and show you how other people are actually seeing the same events.
00:00 - Introduction to the Guest and Firm
01:13 - A Meandering Path: Princeton, the Nasdaq, and Goldman Sachs
03:29 - Back to Basics: What Long-Term Investing Requires
05:22 - Why the Dot-Com Bust Was the Formative Crash
08:50 - Politics, Government, and the Limits of Prediction
12:13 - Baltimore as an Investing Lens
17:33 - What a Law Degree Teaches (and What It Doesn’t)
20:32 - The Junior People Who Rise Fastest
24:49 - The Armchair Psychologist Side of Client Work
27:10 - The Contrarian Take: Private Markets and the Retail Push
31:01 - How to Read: Local Papers from Places You Don’t Live
33:01 - Conclusion and Final Thoughts
