


2026-11-14 17:00:44
“Partisanship is a helluva drug,” as they say. When your preferred party is in power, the sun seems to shine a little brighter, the birds sing a little more sweetly, and there’s a spring in your step as you walk past the homeless encampments and sterile single-family-home-only neighborhoods of your American city. Foreigners from countries where politics is less contentious, like Japan, will never know this joy.
Anyway, this natural partisan sentiment makes it very hard for me to write about developments in American politics. I would like to give you some analysis that’s more informative than “Yay, Democrats won an election!”. I do consider myself a Democrat, after all (even though I’m registered as an Independent). There has never been a point in my entire life when I’d have told you that the Republican presidential candidate was a better pick than the Democrat (though 2012 was fairly close). I regularly bemoan the state of the Democratic Party, but somehow the Republicans always find some way to be Even Worse.
This has been the unfortunate reality for most people in America for years now. Disgust and dissatisfaction with both parties have grown, as both have become more extremist. But there was little they could do except keep voting for the lesser of two evils, while tuning out political news and expressing anger at the whole system. It got so bad that in my New Year’s essay, I even entertained the notion that liberal democracy itself had suffered a generational failure:
To be honest, I still entertain that notion. Reading that essay again, there’s not much I would change. But on the margin, recent events have made me feel more optimistic about where American politics is going.
A lot of this is downstream of the midterm elections. Trump has turned the Republican Party into something truly awful, and it’s refreshing to see America punish the GOP for going along with that transformation:
But my optimism isn’t just about the fact that Democrats won — it’s also about how they won, and what they seem likely to do with their victory. Here I’ve been pleasantly surprised so far. And there are also some scattered signs that our leaders are starting to take our substantive policy challenges more seriously, instead of just relying on partisanship and culture wars. Basically, I see three broad positive trends:
The Democrats are not becoming extremist at the rate I had feared.
There is some real bipartisan movement on good policymaking at the federal level.
The nation is waking up to the problem of corruption, and holding the perpetrators to account.
Over the past few years, I’ve watched the emergence of a leftist faction within the Democratic Party, which I’ve likened to MAGA on the right. This faction had its roots in the Bernie insurgency of 2016-2020, but it has grown beyond that. The Palestine movement both invigorated the leftists and radicalized them, shifting the locus of power in left-of-center activism away from Black activists, identitarian movements, and anti-capitalism, and toward explicitly anti-American “decolonial” ideas.
As recently as this summer, I believed that a Democratic victory in the midterms would be led by this hard-left vanguard:
Here’s what I wrote:
Democrats have spent their political capital moving to the left…[They are selecting] candidates who are so far to the left that they end up frightening and/or offending many voters, and then basically daring people to keep voting for the Republicans…
When DSA-type candidates were just winning in deep blue cities, it was possible to think that they would remain a small, limited faction within the party. But Francesca Hong is going to be the Democratic nominee in a statewide race. So is Abdul El-Sayed, who, while not a member of the DSA, is closely aligned with them (especially on Israel, which he focuses on a lot)…This, increasingly, is who the Democrats are now.
Well, happily, I was wrong about this. Francesca Hong was actually defeated in the Democratic primary race just a few days later in a stunning upset, showing that even partisan Democrats aren’t sold on the DSA faction.
Even more importantly, the hard left didn’t end up leading the anti-Trump charge in the midterms, as I had expected. Despite the blue wave, most of the high-profile DSA-faction candidates performed significantly worse than their normie Democrat counterparts. Jeff Maurer has great data on this:
And the same voters who powered the big Democratic victories also endorsed a lot of centrist policies at the ballot box. Here’s the Washington Post:
Voters in North Carolina elected a Democratic senator…giving former governor Roy Cooper an overwhelming win. At the same time, they approved three [Republican] measures…The first would add a constitutional requirement for a levy limit on property taxes…The second would cap the state income tax at 3.5 percent…The third would require photo ID for voting…
In Wisconsin, Democrat David Crowley won the gubernatorial election…Those same voters approved an initiative…to ban affirmative action in state institutions…Iowa voters elected Democrats as governor and senator while amending their constitution to make it substantially harder to raise state income taxes…Ohio….went blue for Senate and governor. At the same time, two-thirds of voters backed an amendment to require photo ID for voting…
Moderates and independents drove Democratic gains in all these places.
Voters in several blue and purple states also approved measures to restrict women’s sports teams by biological sex.
There’s also a general indefinable “vibe shift” in the air. Anecdotally, people I talk to are less ashamed to voice full-throated support for the kind of liberalism that Barack Obama typified in the early 2010s. Meanwhile, liberal influencers online are beginning to push back more strongly on leftist shouters.
And in Congress, the sheer scale of the Democrats’ victory means that the DSA faction will be effectively disempowered. Because marginal victories tend to be won by moderates in purple states, the leadership in both the House and the Senate is likely to be held by moderates like Hakeem Jeffries and Chuck Schumer. This is driving the DSA factionalist types apoplectic with rage:
Note that the knives are already coming out for Jon Ossoff, whose potential as a 2028 presidential contender surged after his massive midterm victory. But who can leftists run against Ossoff? Enthusiasm around AOC has dimmed, and there’s no obvious replacement.
If they fail to find a candidate for 2028, and if Democrats take back the White House with a normie liberal, the leftist faction faces the real possibility that the window of America’s decade of unrest will limp to a close without them. That would, of course, be good for the nation.
Even moderate politicians, of course, often support unworkable or inadvisable policies. On the Democratic side, the worst problems are anti-development policies at the state and local level. “Progressive” policies have made it prohibitively difficult and/or expensive to build housing, roads, trains, power stations, and transmission lines across much of the country, freezing our built environment in the 1970s. I’ve been loudly complaining about this for years now:
This was a big part of my pessimism about politics. What’s the use of kicking out the Republicans, if the Democrats are just going to decide that “open space” and historic gas stations are more important than giving the middle class a place to live and power for their homes?
Now there are signs that at long last, America’s leaders recognize this problem and are taking action to fix it.
2026-11-13 15:10:54
I was busy with rabbit stuff today, so my next post will be delayed until tomorrow! In the meantime, have another episode of Hexapodia, my revitalized podcast with Brad DeLong.
In today’s episode, Brad and I discuss the question of whether and how to reindustrialize the United States. Brad wrote a whole book on this topic, in fact. Basically, there are three main reasons we might want to boost American manufacturing:
Geopolitical and military reasons: Having a supply chain for defense manufacturing and dual-use manufacturing that isn’t dominated by China would allow us to actually fight a war against China, if we ever had to do that. And since China has shown themselves perfectly willing to use export controls to bully other countries (including ours), we should develop supply chains that China can’t dominate, in order to avoid being bullied.
Economic growth reasons: Having a robust manufacturing sector, in addition to a robust service sector, may make our country richer, by adding agglomeration and clustering effects.
Economic equality reasons: We might want good high-paying blue-collar manufacturing jobs to help revitalize the American middle class.
Brad and I basically think that #3 is a dead end here — it’s not going to work. Especially with the advent of AI and AI-driven robotics, most manufacturing is going to be mostly automated; there will be no way for America to be competitive using human hands in factories when robot hands work so much better. That means the era of mass semi-skilled blue-collar factory employment is simply over and done.
But that doesn’t mean that manufacturing can’t create jobs. They just have to be different kinds of jobs — for example, local service jobs created by the money that the automated factories bring in to a town. That’s called a “local multiplier” effect, and it’s very powerful and important. Of course, it’ll require that the people who run the factories live near them, so they can spend their money locally.
Which leaves geopolitics and security as the main driver of reindustrialization. We note that the one country that we know of that has ever successfully reindustrialized was Ukraine, which built a strong drone and robotics industry out of necessity in order to fight off the Russian invasion. It’s not necessarily the most optimistic example for us to look to, but it may be the most important.
Anyway, Brad and I then spend a long time discussing what, exactly, America needs to reindustrialize. We come to the tentative conclusion that America really lacks only two important things — land use, and bank loans.
Land use, of course, is what the permitting bill currently moving through Congress is meant to address, and it’s important for a whole lot of other things besides manufacturing.
Bank finance seems to be important for manufacturing for a whole lot of reasons (expect more blog posts about this in the near future), and this is one area where America really struggles compared to other countries. My idea is to use America’s moribund megabanks as pools of capital for reindustrialization by giving them selective exemptions from the Dodd-Frank restrictions enacted after the financial crisis of 2008. More on that later.
2026-11-11 16:51:56
My last post was about how for the first time, I’m becoming bearish on China’s continued economic and technological outperformance. A number of people asked me whether I was similarly bearish about India. The answer is no — I’m actually more bullish on India than I have been in a while. In fact, I had been meaning to write a post about that, so this gives me a good opportunity to do so.
The reason I’m bullish on India and bearish on China is that we’re asking the two countries to do two different things. When we think of China’s future success, we think of whether it’ll eclipse the combined economies of the U.S. and its allies, seize the lead in artificial intelligence, reach Taiwan or Korea’s level of income, or dominate Asia. I’m increasingly skeptical about its ability to do all of those things. But India’s job right now is a lot simpler — it just has to escape poverty and become an upper middle income country. And this I think it can do.
In both GDP terms and in terms of the Human Development Index (which combines GDP with education and health), India is around where China was in the late 2000s.
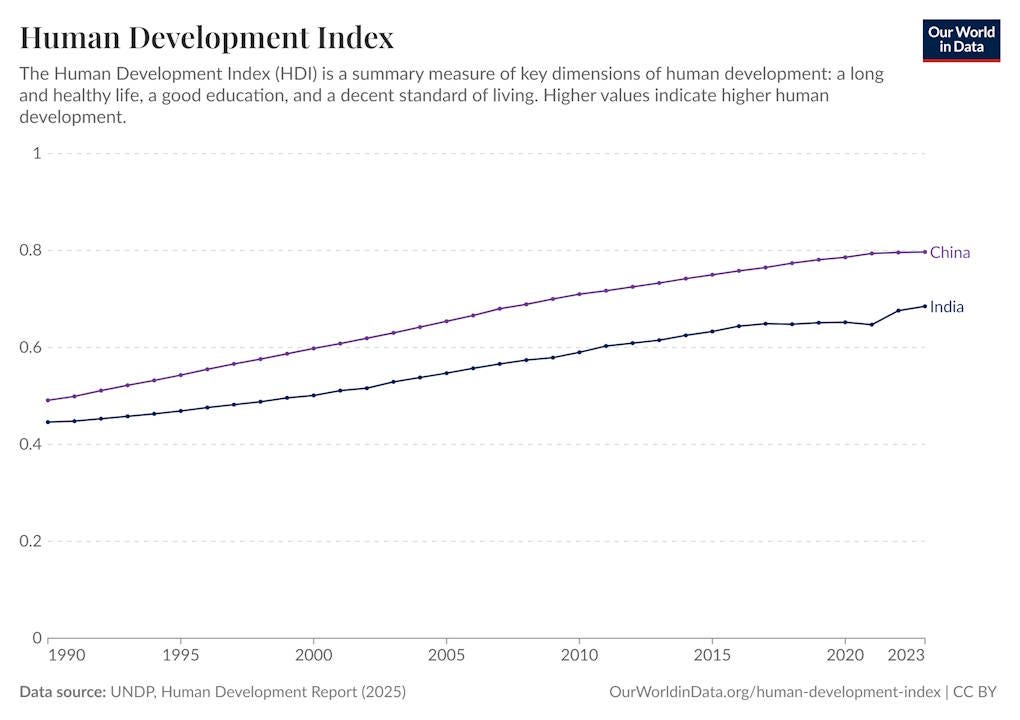
It’s easy to forget, but in the 2000s, people still thought of China as a basically developing country — its cities choked with smog, its rural areas still mired in poverty, its economy driven by cheap labor and lax environmental protections, and so forth. The challenge now for India is to make the leap that China made in the 2010s — to build abundant high-quality roads, trains, housing, and energy, provide decent jobs and livelihoods to the majority of its people, and catch up to the frontier of technology.
A lot of people don’t seem to realize how good of a start India has made. For one thing, extreme poverty in India has mostly been conquered over the last two decades:
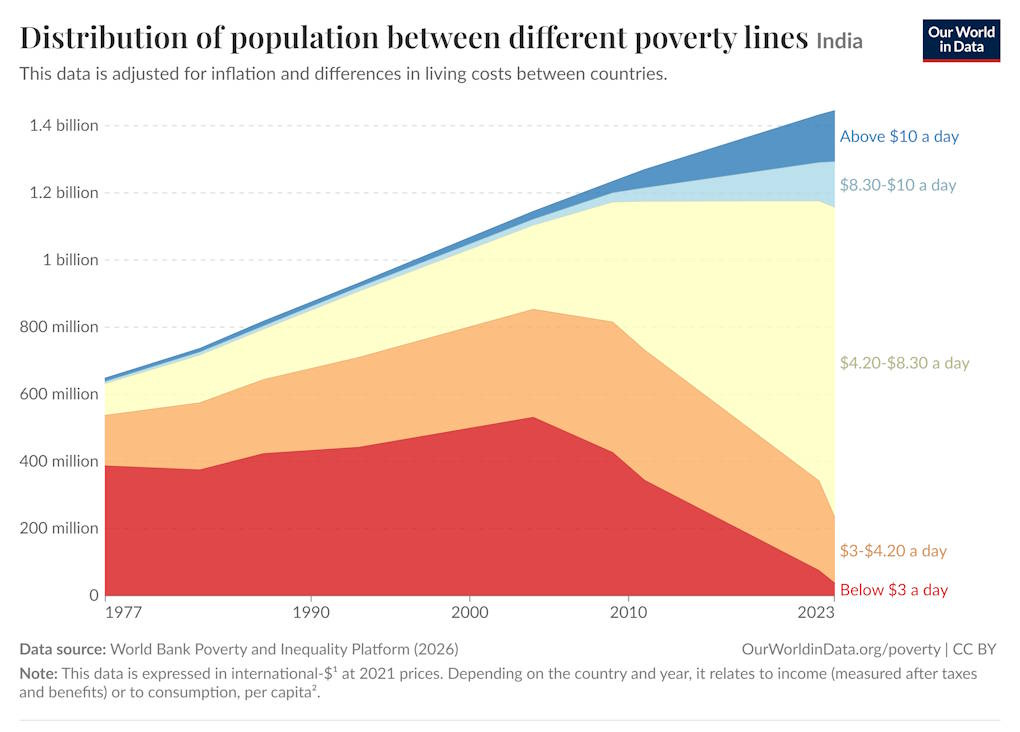
This is an incredible accomplishment — a full tenth of humanity saved from deprivation. And what’s remarkable is that — unlike China — India managed to do this incredible poverty reduction while also reducing inequality:
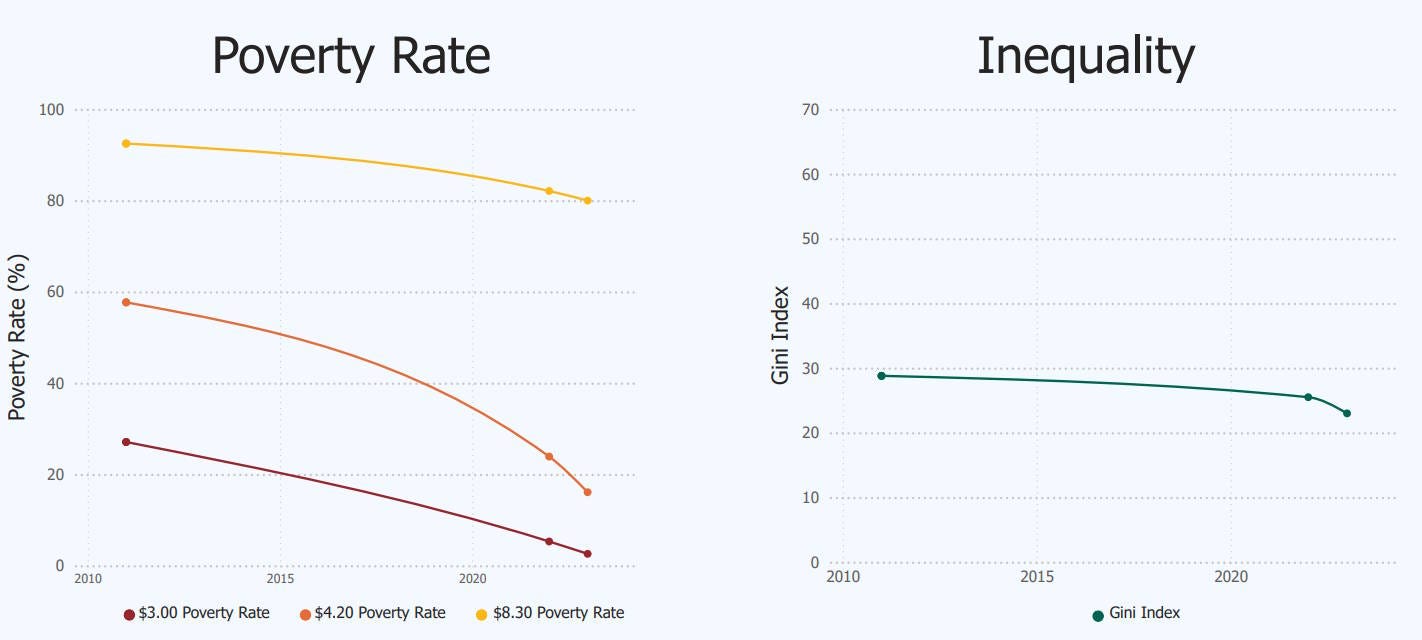
How did India manage this feat? The World Bank says that it was due to the two usual suspects — economic growth and redistribution:
Over the past decade, India has made remarkable progress in reducing poverty across both monetary and non-monetary dimensions, recording one of the fastest poverty declines in the world…This progress was mainly driven by strong consumption growth, rising employment, especially among women, and expanded social transfers, including food subsidies. [emphasis mine]
A strong welfare state is certainly important, but economic growth has to take the lion’s share of the credit here; without growth, there’s simply less of a pie to redistribute in the first place. And India’s growth has certainly been impressive. Ever since the pandemic, India has been growing faster than China:
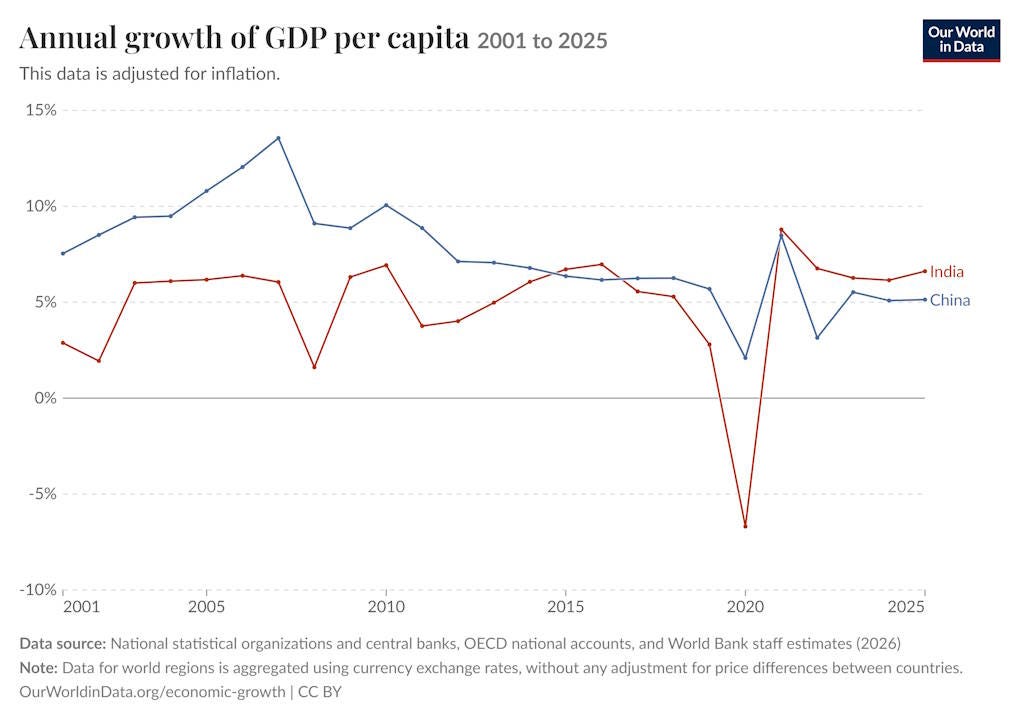
Now, India isn’t growing as fast as China did when China was at $10,000 of per capita GDP. Back in the late 2000s and early 2010s, China was still growing at close to double-digit rates; it didn’t slow down to India’s current rate until 2014, at which point it was 40% richer than India is now. But 6.5% is still a very healthy growth rate — it represents almost a doubling of living standards every decade.
And Bloomberg expects Indian growth to accelerate even further, to 8% by the end of the decade. Neelkanth Mishra, the executive director of the World Bank, points out that because India’s recovery from the pandemic recession is still incomplete, there’s plenty of room for a growth acceleration.
You’d expect this kind of growth to transform every part of Indian society and culture, and this appears to be exactly what’s happening. Arjun Ramani has a great in-depth report from his travels across India, focusing on how economic development is changing life on the ground:
How is India producing this rapid growth? India is long past the point where you can tell a simple story about the country’s economic progress — manufacturing, finance, real estate, business services, IT, and a bunch of other sectors are all growing at once.
How is India managing to grow so fast? The Economist mostly credits liberalizing reforms and prudent macroeconomic policy:
A programme of fiscal consolidation has cut the budget deficit from 9.2% of gdp in fiscal 2021 (when it was bloated by pandemic spending) towards a target of 4.4% for fiscal 2026. Excluding interest payments, the deficit will be only around 0.9% of gdp…With inflation under control, interest rates have been cut by 1.25 percentage points over the past year…
The decline in inflation is not just limited to food, points out Sonal Varma of Nomura, a bank. Earlier reforms, such as the creation of a digital-payments infrastructure, which made prices more transparent, as well as the RBI’s shift to an inflation-targeting regime in 2016, have helped reduce inflation expectations and are now paying off. The RBI has also built up its stock of foreign-exchange reserves. A banking sector clean-up and reforms to the bankruptcy code have kept the financial system stable…
The longer term looks even more promising, thanks to a vigorous reform effort…A long-mooted cut in the number of labour codes, from 29 to four, was enacted in November. A cap of 74% on foreign direct investment in the insurance industry has been lifted. Nuclear power has been opened up to the private sector. Financial-market regulation has been overhauled…The states have also pursued reforms. Allowing women to work after dark, for instance, means textile and electronics factories can stay open later.
I have to say, I’m skeptical of this story. Fiscal probity is well and good, but India’s long-term borrowing rates haven’t come down all that much:
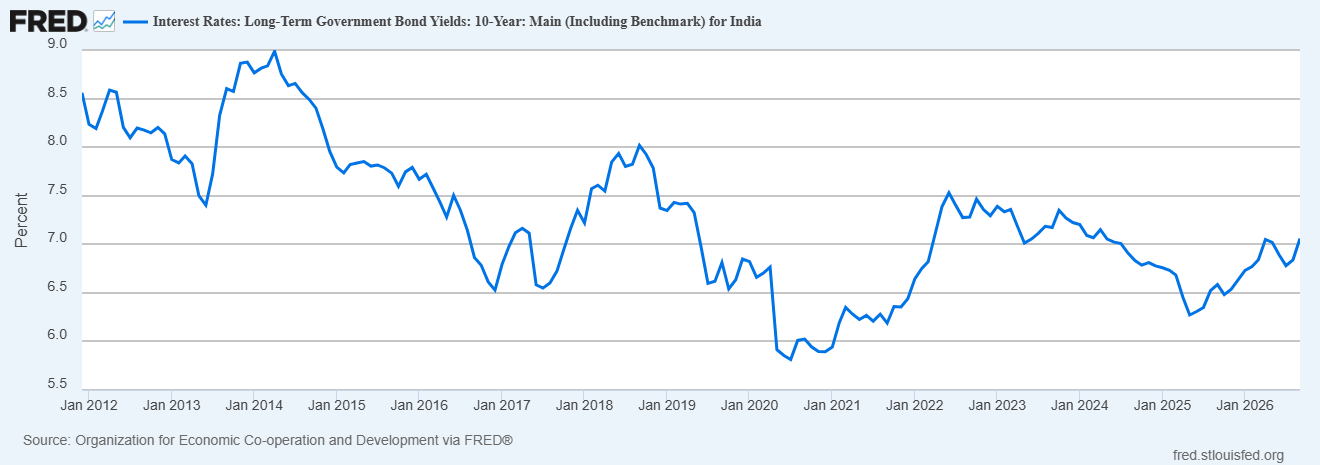
A stable financial system is very good, but it’s not clear how that automatically accelerates growth. And most of the real structural reform The Economist mentions is in the future. It’s possible for businesses’ expectations of structural reform to drive growth, but as the article mentions, domestic private-sector investment isn’t really driving the boom. FDI is sluggish too (or at least was until this year).
One bright spot is government investment, which has increased by a factor of four since before the pandemic, in spite of the country’s falling debt levels:
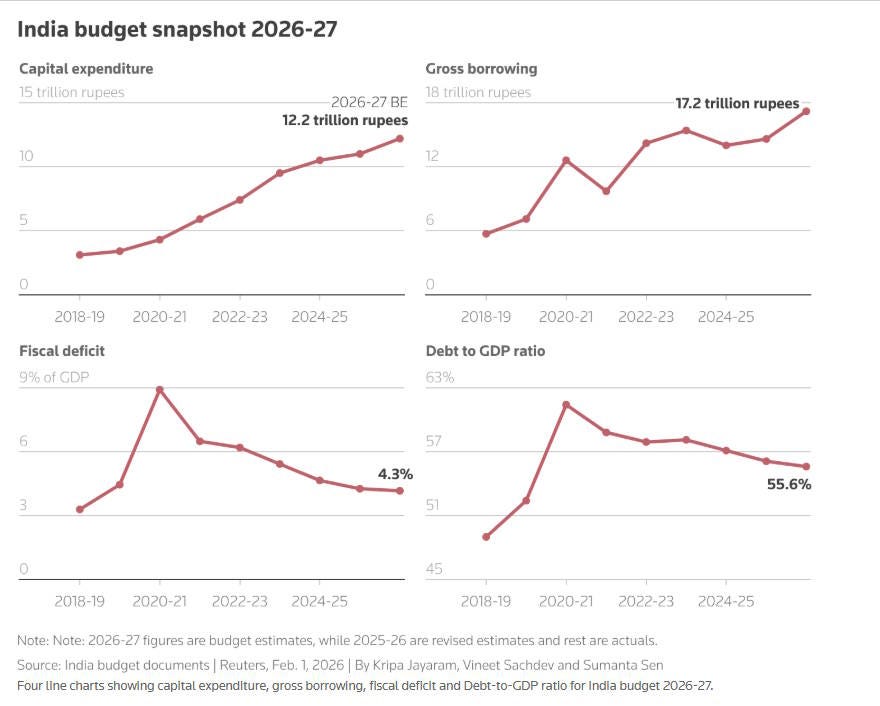
The Indian government has been on a tremendous infrastructure-building boom — correcting one of the country’s notorious chronic deficiencies. Highway spending has increased by a factor of five over the last decade. Central government railway spending has risen eightfold.
This is boosting growth in the short term, but in the long term it’ll make both manufacturing and consumption a lot easier in India. It’s also changing the physical look and feel of the country, much as China’s own modernization did in the 2000s and 2010s (if not as rapidly). India is now building its own bullet trains:
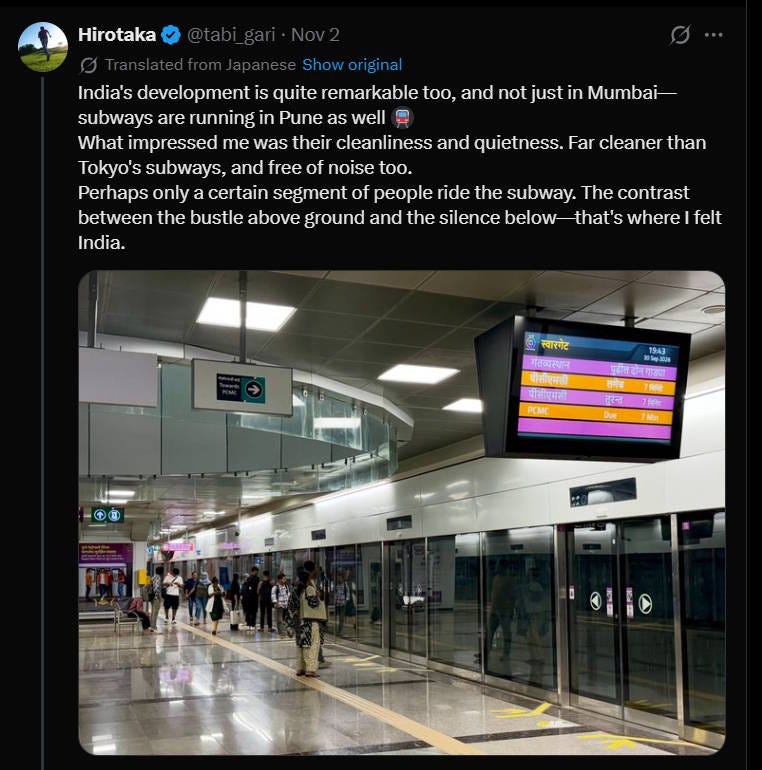
I recently saw an example of a Japanese man who declared that he was impressed by how clean and quiet Indian subways were, compared to Japanese ones!
Another important factor in India’s growth story — and another long-standing deficiency that’s now beginning to be corrected — is the growth in Indian manufacturing.
The old story of India’s economy is that it had “leapfrogged” manufacturing and gone straight to services — call centers, business process outsourcing, software outsourcing, and the like. That concealed a quiet disappointment that India hadn’t managed to get on the same industrialization bus that has carried so many other countries out of poverty. But India’s current growth is very broad-based — manufacturing is growing right alongside services. The Economist has some details:
Manufacturing output in August, the most recent figure available, was 9% higher than the year before, thanks in particular to surging production of cars and electronics…India’s rising manufacturing output…reflects its growing appeal as a place to make things. In dollar terms India’s electronics exports were up by 90% in August, year on year, with American-bound iPhones accounting for a large share of that.
Another encouraging sign is the breadth of India’s manufacturing growth. Whereas Bangladesh’s manufacturing boom last decade was powered mostly by the garment industry, India is making and exporting a bunch of different high-tech products:
The strength of India’s engineering exports lies partly in the diversity of its product segments. Automobiles remained the largest contributor in FY 2025–26, accounting for 21.9% of total engineering exports. Industrial machinery followed with an 18% share, while iron and steel products accounted for 16.9%…Electrical machinery contributed 12.5%, other engineering products 12.7%, and non-ferrous metals and products 11.6%.
And keep in mind, this is all in spite of China’s attempts to throttle Indian industrialization by denying them key technological exports and factory expertise. Competitive pressure from a more established economic power is not something China itself had to deal with, since the U.S. wholeheartedly supported China’s industrialization in the 1990s and 2000s.
Whether India’s growth boom can continue past the next couple of years is an open question. Private investment will have to rise, and probably FDI as well. India is also going to need to correct its bigger structural issues at some point — especially bad rural education, female underemployment, and incomplete urbanization.
But for now, India looks like a big economic success story — perhaps the brightest in the entire world right now. It’s less visible than China’s rapid rise two decades earlier, but it’ll be no less world-shaking when it happens. More people should be taking notice.
2026-11-10 07:01:29
Azeem Azhar of Exponential View is an excellent blogger whom I tend to cite a lot. So it was very fun to call him up and talk to him about the AI boom, and the possibility of an AI bust! The discussion was sparked by this post of mine a few weeks ago:
I don’t think we reached any firm conclusions, but it was fun to mull these issues over. Expect more discussions between me and Azeem in the future!
2026-11-09 15:59:29
Many longtime fans of my Hexapodia podcast with Brad DeLong have been begging us to bring it back. Well, here it is! Hexapodia will now be a series of Substack Live conversations that you can tune in to, and which will be recorded as podcasts and sent out as emails.
Our first episode was a little rocky, as I got the time wrong and ended up arriving 20 minutes late. But Dan and Brad are both brilliant people, so you can watch them talk for a while before I show up! The topic of our discussion was the Anthropic IPO, inspired by my post about it last week:
I give the bull case for Anthropic, while Dan and Brad are both more skeptical. I think this quote sums up my side of the argument:
My bull case [for Anthropic] is not envisioning a world where Anthropic rules all businesses, rules 100% of every industry, or close to it. I’m also not envisioning a case where AI replaces human beings in their jobs.
I’m envisioning a change in the capital structure of the efficiently producing economy. I’m envisioning…a world where in order to succeed in any industry, you must create a tie-up with a frontier AI company that offers you access to an internal proprietary frontier model that will be months ahead of any model distilled from it. And…that doing this will require not purchasing services…at arm’s length from that company, but tying up your capital structure with that company so that you become in some sense a subsidiary of that company. I am envisioning that.
So I’m saying that instead of something where…AI is like oil and everyone has to buy oil or the things made downstream from oil…instead of that sort of arm of length world, I’m envisioning a world in which every company in order to succeed must become a subsidiary of Anthropic, OpenAI, [or] Google…and Anthropic is simply the biggest of those fish in a oligopolistic ecosystem of a few conglomerates competing against each other via their little subsidiaries in every single industry at the same time.
Interestingly, some economists at Google Deepmind just released a paper with a model in which this sort of thing happens. From the abstract of Imas, Koh, and Legg (2026):
When will advances in AI lead to economic transformation? We develop a model of how intelligence…matters for organizations….AI expertise is reproducible while humans’ are in fixed supply, and AIs may not face the same human limits on coordination….When AI is more capable than the average human, organizations of complementary humans can nonetheless outperform AI. Increases in AI competence can change the composition of workers within firms and decrease firm size. As AI coordination improves, however, this can break the Coasean ceiling on firm size and the market structure undergoes a phase transition toward large, concentrated AI-heavy firms. [emphasis mine]
I was envisioning a slightly more complex version, in which humans and AI are complements, where humans have private data that AI is better at using, and where one big conglomerate enters every industry but retains human workers. But I think Imas et al.’s model gets at some of the basic dynamics here.
Financial disclosure: I have no current position in Anthropic, but unless something major changes, I will probably buy Anthropic stock when it IPOs. I own stock in TypeSafe, an Anthropic competitor.
2026-11-08 05:11:43
When I tell people I’m becoming a China bear, they’re often surprised. “Weren’t you already a China bear?” they ask me.
Well, no. I’ve always been a China bull — I’ve always believed that China’s economic growth would be robust, that they would master advanced technologies, and that their geopolitical influence would grow. This is exactly why I was also always a China hawk1 — I recognized the very real possibility that China would become a global hegemon, and I didn’t especially want to live in a world ruled from Beijing. It’s why I advocated so strongly for friend-shoring, for export controls, and for military alliances to balance out China’s awesome and growing power.
This was true even as China began to show visible signs of weakness in the late 2010s and early 2020s. Xi Jinping proved himself less competent than his predecessors, and the country’s real-estate-heavy growth model hit the skids. But despite those stumbling blocks, I still predicted that this would be the Chinese Century. The country had what seemed like unassailable advantages in human capital, market size, and state capacity, even as all of its possible rivals were convulsed by internal division. And the one thing that most people cite as China’s big weakness — demographic decline — never struck me as much of a threat to the country’s power.
Now, however, for the first time I can remember, I’ve found myself becoming actually bearish on China. I still think it will be an immensely powerful country — perhaps the most powerful single country on the planet. I still think it will be at or near the forefront of technology, and that it will generally be a safe, moderately prosperous, and tolerable place for its people to live. But more and more, I’m starting to think that global hegemony of the type the U.S. enjoyed throughout most of the 20th century will be out of reach. I’m also starting to think that China’s bid for technological dominance is weaker than I had believed.
And just as my previous bullishness made me a hawk, my increasing bearishness makes me more of a China dove.2 I still think friend-shoring is important, export controls are good, and we need robust military alliances to make very sure China doesn’t try to conquer Asia. But I no longer feel the same sense of desperate urgency about these prudent measures — they feel more like an insurance policy now.
There are basically three reasons I’m revising my China expectations downward. The biggest reason is AI. China’s system is incredibly optimized for an era of technology and economic production that is very quickly coming to an end. AI will change everything, and modern China is not the kind of country that adapts well when everything changes.
The other reasons are less important but still worth mentioning. China’s new economic model — the government-supported push to capture all of global high-tech manufacturing — is not likely to succeed. And third, the country’s political situation appears to be deteriorating. Just as the Deng/Jiang/Hu era illustrated the strengths of authoritarian political systems, Xi Jinping is giving us a much-needed lesson on the weaknesses of those systems. His spiraling paranoia is turning the country inward, just as his economic policies are running out of steam.
Anyway, let’s start with those economic policies. This is an economics blog, after all.
In a nutshell, Xi Jinping’s economic strategy is to dominate manufacturing — to have China be, in the words of Damien Ma, the “make-everything country”. I’m increasingly convinced that this approach is already beginning to backfire.
Going all-in on manufacturing is a strategy you see a lot of developing countries use during their periods of rapid catch-up industrialization. And there are some good reasons for that. When you’re poor, what your people need most aren’t video games or dog-walking services, but houses and cars and refrigerators. Manufactured products are also easy to export, and poor countries don’t have big domestic markets to rely on. It might also be easier to reach the technological frontier in manufacturing, since you can reverse-engineer physical products more easily than services.3
Usually, as countries get rich and their needs evolve from the physical to the ephemeral, they move out of manufacturing and into services to some degree. But Xi Jinping decided that this was a mistake. He reasoned that if China continued to behave like a developing country forever, and promoted manufacturing at the expense of everything else, China could dominate the globe.
This was an interesting hypothesis, and it might have worked — indeed, there’s still some chance it might work. Militaries, after all, depend on manufacturing above all else, so in a big protracted WW2-style war, being the master of manufacturing might give you an automatic win.
And dominating key nodes in global supply chains lets you use export controls to bully other countries without actually bombing them. In fact, China is doing this more and more, using export controls on everything from tunnel-boring machines to rare earths to drones to medicines as bludgeons to force other nations to do its bidding.
In order to make China dominate global manufacturing, Xi unleashed a wave of industrial policy bigger than any the world had ever seen, spending about 4% of GDP per year on subsidizing manufacturing industries — usually through cheap bank loans, but sometimes just by sending cash directly.
For a while, this seemed to be working spectacularly. A 2024 paper by UNIDO got a lot of attention for predicting that China’s share of global manufacturing would be 45% by 2030 — equal to the United States right after World War 2. But cooler heads pointed out that China’s manufacturing share growth had already slowed; more reasonable predictions put its 2030 share at maybe 35-36% — still enormous, but more like America in the 1960s or the early 1920s.
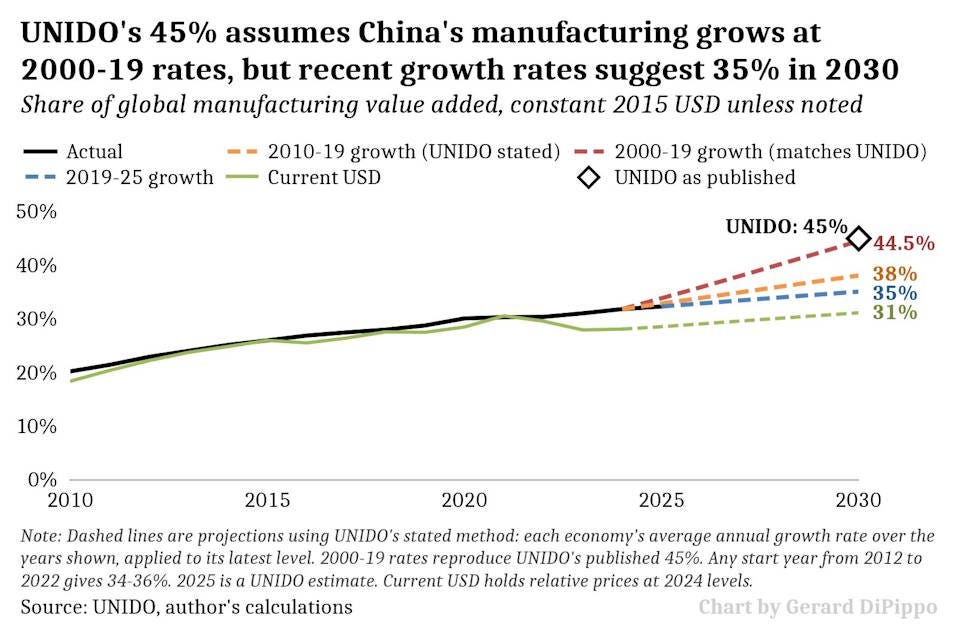
And in U.S. dollar terms, China’s share peaked during the pandemic and has been drifting down since then:
In fact, despite Xi’s push, manufacturing is a shrinking share of China’s economy. China is now less industrial than South Korea, despite being less than half as rich:
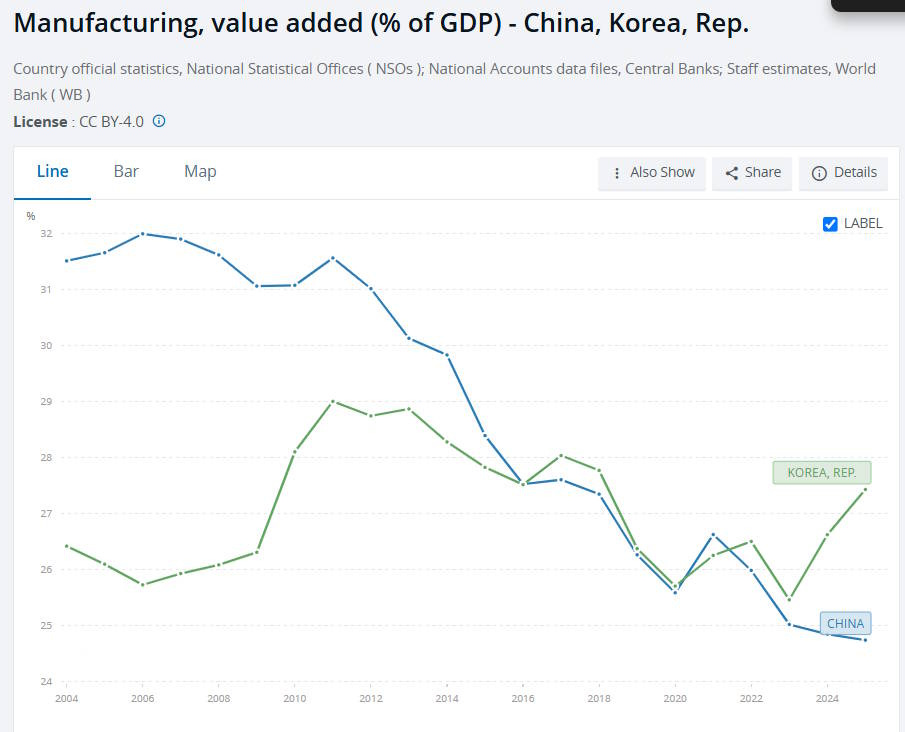
The reason is simple, and it’s something I’ve written about many times before. Unlike South Korea, China is a very large country. That means most of China’s manufacturing production is going to have to go to the domestic market. Even if other countries don’t slap big tariffs on your products, export markets will simply saturate. One of the most reliable empirical laws in all of economics is the gravity model of trade, which says that trade volumes drop off rapidly with distance.
Of course, some countries will put tariffs on China. The EU recently forced China to make a deal to limit auto imports, and if that doesn’t work, stronger measures are likely. That will only accelerate the natural saturation of China’s export markets.
And despite everything you’ve read about the “Second China Shock” and the big export boom, China is still far less export-intensive than Korea, and that’s not going to change:
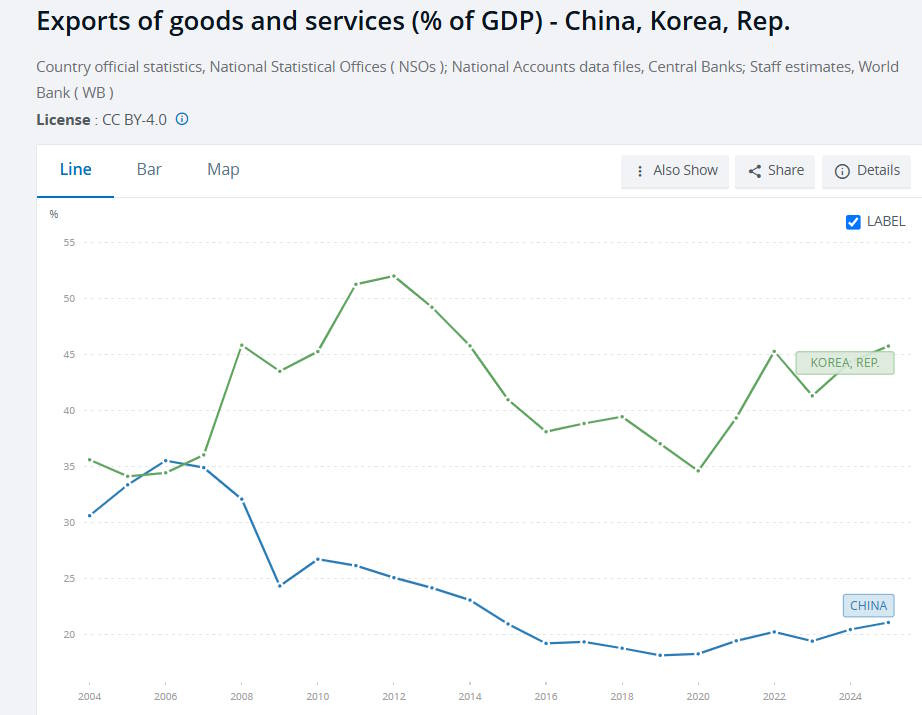
China simply can’t be Giant Korea; it’s so big that its manufacturers need to rely on its domestic market. But that domestic market is becoming saturated even faster than the global market. Profits in the auto sector, the steel sector, the solar sector, and many other manufacturing industries are all collapsing. Weak domestic demand from China’s real estate bust has encountered massive oversupply from government subsidies, and the result is that few companies in China are making much money. That will force lots of businesses to close and consolidate, and it will starve dynamic private-sector companies of R&D budgets, forcing them to rely more on research handed down by the distant, unresponsive, and unaccountable government.
Government subsidies can keep the party going a lot longer than it ought to, but already the limits have probably been reached. Chinese manufacturing indicators are faltering, and manufacturing investment seems to have topped out as well.
In fact, this isn’t even the only example of Xi Jinping taking a developing-country strategy and pushing it far beyond its limits. Infrastructure is another. For many years, China invested huge amounts into building more roads and bridges and high-speed trains than they knew what to do with. But there was a limit to that process, and China has now hit the limit. The Economist reports that China’s infrastructure investment has leveled off:
China’s years-long splurge on bridges, tunnels, expressways, high-speed rail and airports is beginning to tail off…In July this year a senior transport official said China’s main transport network was “91% complete”, and the country would pivot from expanding to upgrading existing infrastructure.
But it isn’t so easy weaning yourself off of infrastructure overinvestment. China built so much infrastructure that it will have to spend a lot of money just to upkeep all those roads, trains, and bridges. That’s the iron logic of depreciation. And since much of China’s infrastructure isn’t really carrying many passengers or much cargo, that means China is stuck spending a significant fraction of its GDP upkeeping stuff that people don’t really need — unless, of course, it chooses to let some of that infrastructure decay into ruin.
All of this means growth will slow. And of course, it’s all happening against the backdrop of weak demand from the continuing, protracted fallout from China’s real estate bust. There are signs that the real economic damage in that sector is only getting started:
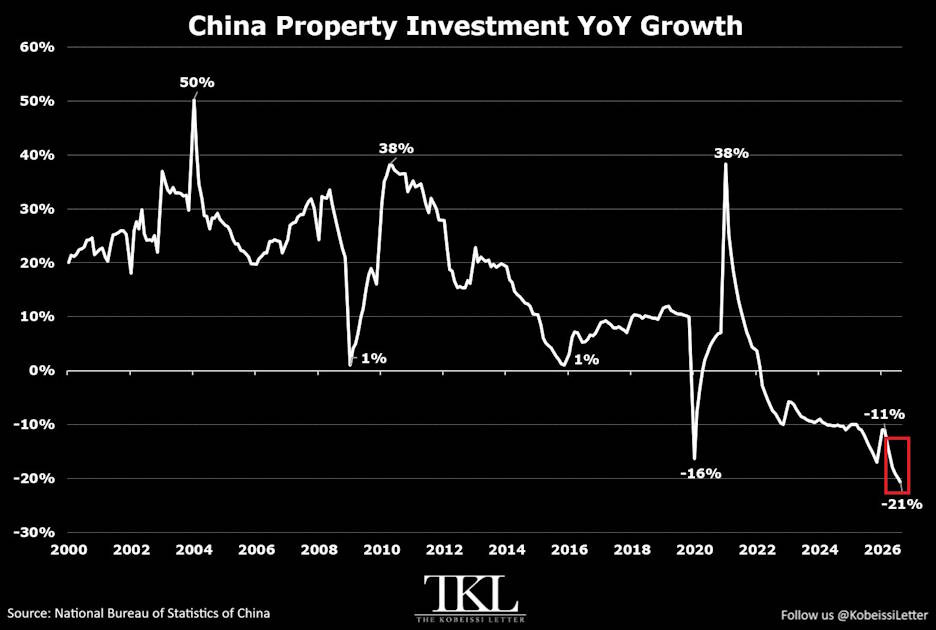
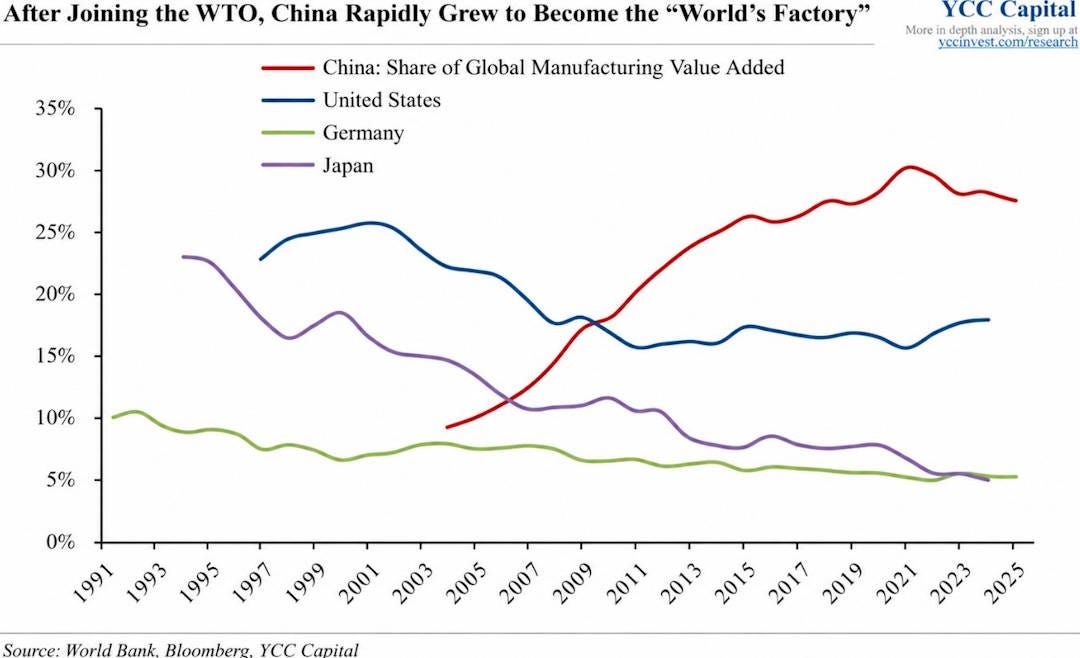
Weak domestic demand won’t just be a drag on China’s headline growth — it will also make it harder for China’s manufacturing sector to maintain its 30% global market share, much less expand it to 35% or more. Xi seems to think that China can just sort of pull resources off of real estate development and put them into manufacturing, one for one, like a corporate manager reassigning engineers to a different project. But it doesn’t work like that; demand matters, and China’s manufacturing triumphs in past decades depended heavily on the tailwind that the long property boom had been delivering.
Chinese economists realize this, but Xi seems to have stopped listening to economists, and to have purged his government of anyone who was inclined to listen.
(And of course as the years go by, China’s accelerating population decline will reduce its domestic market size by more and more, compounding the pressure on manufacturing. I don’t expect this to be a big factor until at least 2040 or so, but it’s worth mentioning.)
In other words, Xi’s “make-everything country” strategy is likely to see only modest short-term success. It will not let China conquer the world. And the failure of this strategy will come just as a massive new technological revolution upends the global economy — a revolution that China, despite all reports, is not well-prepared to take advantage of.


